

Uruguay tax residency through real estate
Uruguay's rules set three property-investment thresholds. Here they are in indexed units (UI) and in today's dollars, with the units for sale that exceed each one.
Which units exceed each thresholdHow much you need to invest
Property-investment thresholds, from lowest to highest.
Tax residency with 60 days in Uruguay
Property bought on or after July 1, 2020, and at least 60 days of physical presence in the year.
More than 3,500,000 UI
about USD 590,000
Foreign income, for eleven years
For people who become residents from 2026 and were not residents in the two previous tax years, nor used the earlier regime. Property bought on or after September 1, 2025; it can be the same property used for residency, and it is certified every year.
You can opt to be taxed under IRNR, which does not tax foreign income, instead of IRPF on dividends and interest from abroad and on gains from selling those assets (derivatives excluded), in the year of arrival and the following ten.
More than 12,500,000 UI
about USD 2,080,000
Tax residency with no minimum stay
Property worth that amount on December 31.
More than 15,000,000 UI
about USD 2,500,000
Without investing, you are also a tax resident if you spend more than 183 days in Uruguay in a calendar year.
The threshold is the total of the properties in your own name (in co-ownership, your share counts): two or more units together also count.
Dollar figures are a reference, rounded up. For residency, what is compared is the tax cost of each property and ownership on December 31, and the test does not apply if tax residency in another country is proven. Since the UI rises every month, it is wise to leave a margin; the tax firm confirms how it applies to you. Dollar figures use the Central Bank of Uruguay's UI (6.6827, 10/30/2026) and banknote dollar rate (40.19, 10/29/2026).
Which units exceed each threshold
Units available today in the developments we sell, sorted by price. The list updates itself with the inventory.
For off-plan units, DGI has accepted a registered purchase commitment for residency; for the foreign-income regime there is no specific rule, so the tax firm confirms it case by case.
More than 3,500,000 UI
From about USD 590,000: tax residency with 60 days in Uruguay.
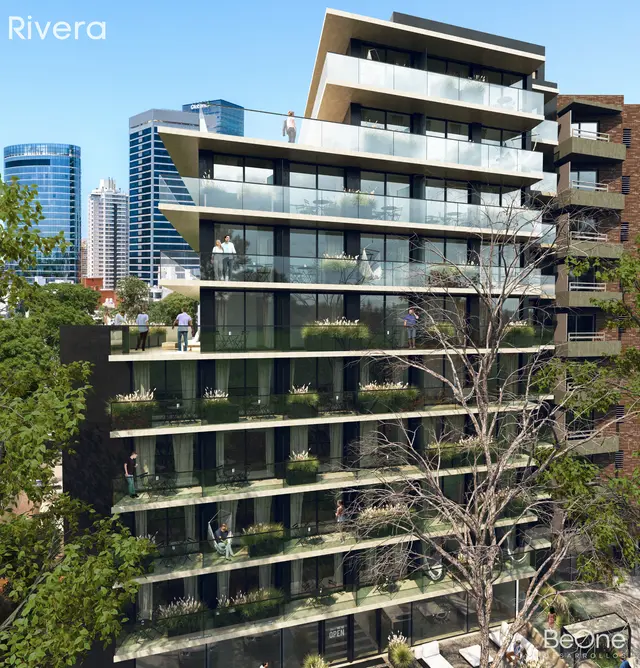

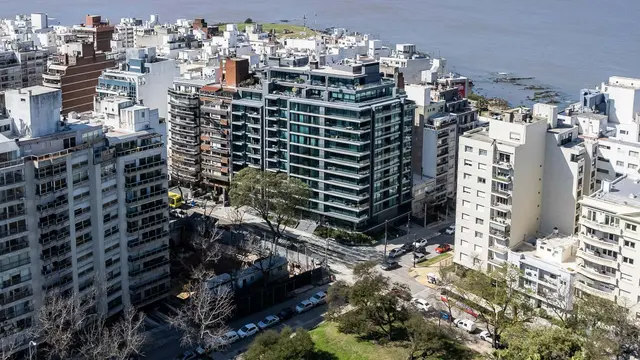
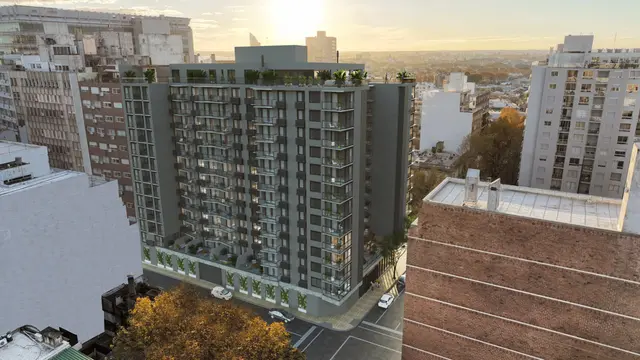
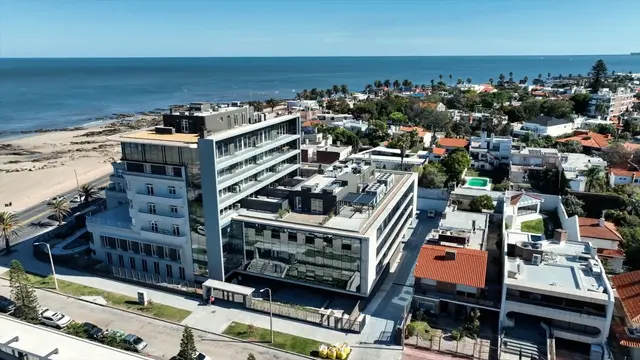
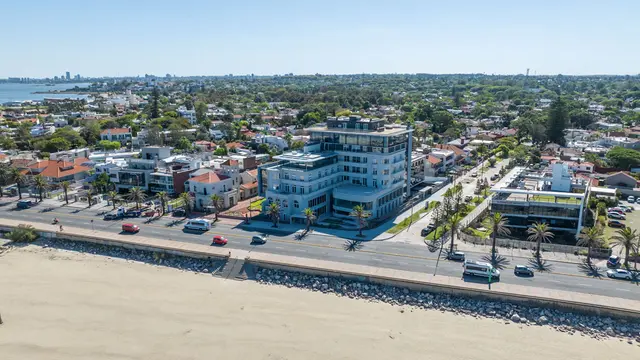
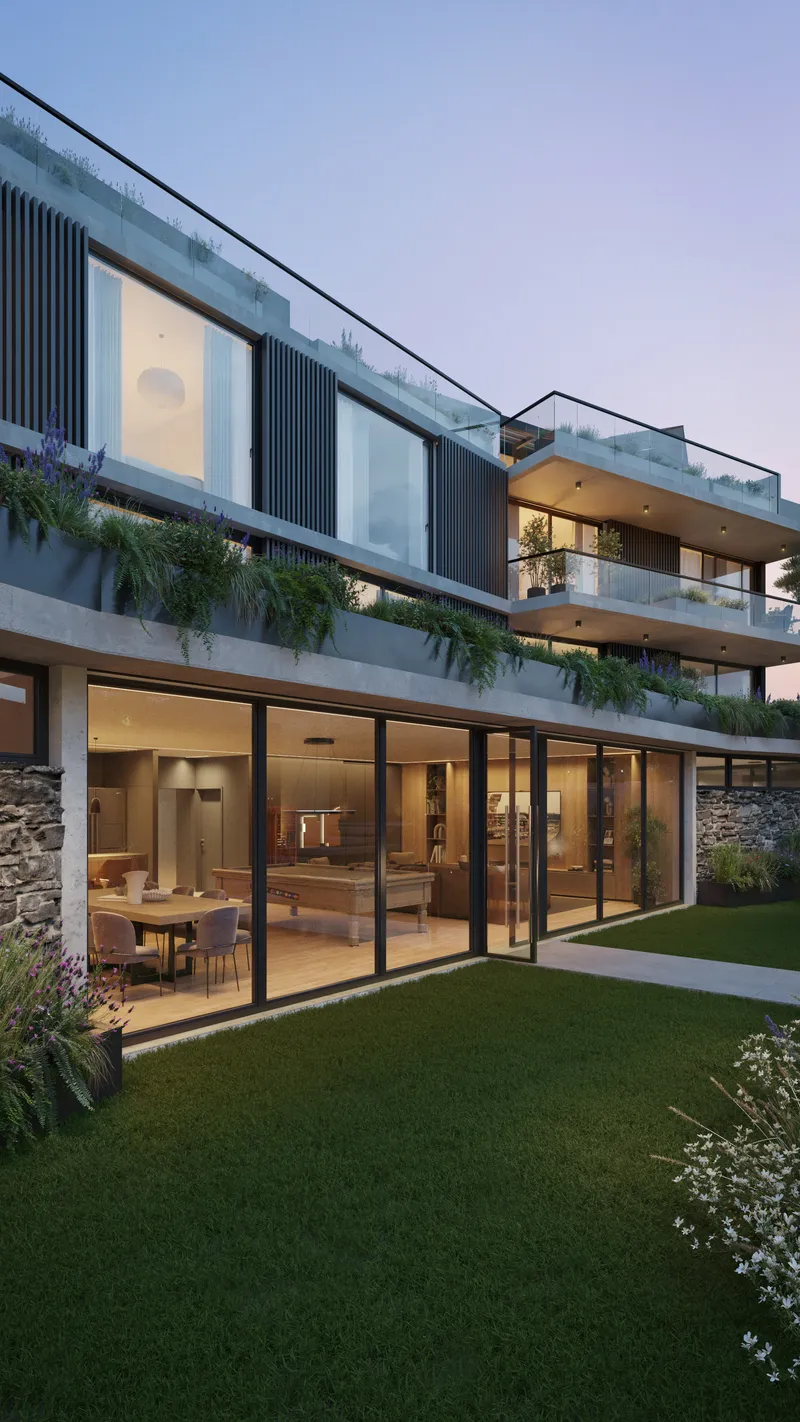
Units with their own page: Bilú Riviera 702
More than 12,500,000 UI
From about USD 2,080,000: the foreign-income regime as well.
More than 15,000,000 UI
From about USD 2,500,000: residency with no minimum stay, plus the foreign-income regime.
If your budget falls short of a threshold
The threshold is the total of your properties: two or more units together also count. We put together options from the current inventory.
How we work
INGAR handles the purchase: searching, comparing, negotiating and coordinating the deed, even if you are abroad. For the residency process we introduce you to the specialist tax firm we work with, which confirms how the rules apply to your case.
Frequently asked questions
Does buying property give me tax residency in Uruguay?
Not automatically. A real-estate investment may establish tax residency through either of two separate tests: holding property worth more than 15,000,000 UI on December 31, with no minimum stay; or holding property worth more than 3,500,000 UI, acquired on or after July 1, 2020, plus at least 60 days of physical presence in the year. What counts is the updated tax cost of each property held in the individual's own name (in co-ownership, their share), and the test does not apply if the person proves tax residency in another country. For off-plan purchases, DGI has accepted a registered purchase commitment. Tax residency and immigration status are separate processes; buying property does not by itself grant legal residency.
What is the Law 20.446 “tax holiday”?
It is an option for people who acquire tax residency from January 1, 2026, who were not tax residents in the two previous tax years and did not use the earlier regime. It allows dividends and interest from abroad, and gains on selling those assets (derivatives excluded), to be taxed under IRNR, which does not tax foreign-source income, instead of IRPF, for the year of the change and the following ten tax years. Depending on the case, Law 20.446 requires an investment above 12,500,000 UI in real estate, annual contributions of at least 625,000 UI to funds under the conditions set by the Ministry of Economy and Finance, or more than 183 days of presence in each tax year; the conditions are certified every year. Under Decree 225/026, the real-estate route counts property acquired on or after September 1, 2025, which may be the same property used for tax residency; the UI is valued at the last day of the month before the investment, and for urban property in departments with no coast on the Río de la Plata or the Atlantic Ocean the tax cost is increased by 100%. This is general information; a tax adviser should confirm how it applies to an individual case.
Sources: DGI, tax residency criteria (Decree 148/007, art. 5 bis); Law 20.446, art. 648; Decree 148/007, art. 5 sexies, as worded by Decrees 188/026 and 225/026. Exchange rates: Central Bank of Uruguay. General information, not tax advice.
Tell us how much you want to invest
Leave your details and we will get back to you to go over which units or combinations exceed the threshold you are after. We also introduce you to the tax firm for the process.
If you prefer, email us at contacto@ingar.com.uy